Updated October 7, 2026.
In today’s world, financial literacy is an essential skill that everyone should possess. Teaching children and young adults about money management from an early age is crucial to their long-term financial well-being.
As parents and educators, it is our responsibility to equip the younger generation with the knowledge and skills necessary to make informed financial decisions. This comprehensive guide aims to provide valuable insights and strategies for teaching money management effectively.
The Importance of Teaching Money Management
Teaching children and young adults about money management is crucial because it empowers them to make informed financial decisions throughout their lives. Without proper guidance, individuals may struggle with budgeting, saving, and debt management, leading to financial stress and difficulties.
By teaching money management skills, parents and educators can equip the younger generation with the tools necessary to achieve financial independence and security.
Starting Early: Introducing Basic Concepts
The Value of Money
One of the fundamental concepts to teach children is the value of money. They should understand that money is earned through work and that it should be used wisely. Introducing the concept of opportunity cost can help children recognize that every financial decision has consequences.
Needs vs. Wants
Teaching children the difference between needs and wants is essential for responsible money management. They should understand that needs, such as food, shelter, and clothing, should take priority over wants, which are non-essential items or activities.
Saving and Spending
Encourage children to develop a habit of saving money by setting aside a portion of their allowance or earnings. Help them understand that saving for future goals is important, while also teaching them about responsible spending on immediate needs and occasional wants.
Setting Financial Goals
Short-term vs. Long-term Goals
Teaching children to set financial goals is a valuable skill. Differentiate between short-term goals, such as buying a new toy, and long-term goals, like saving for college or a car. This distinction helps them understand the importance of planning and delayed gratification.
SMART Goals
Introduce the concept of SMART goals: Specific, Measurable, Achievable, Relevant, and Time-bound. Teach children how to set goals that are realistic and actionable. By incorporating SMART goals, they can track their progress and feel a sense of accomplishment.
Budgeting and Tracking Expenses
Creating a Budget
Teaching children to create a budget is crucial for managing their finances effectively. Help them understand the concept of income and expenses, and guide them in allocating their money wisely. Encourage regular budget reviews and adjustments as their financial circumstances change.
Tracking Income and Expenses
Teach children how to track their income and expenses. This can be done through simple methods, such as using a notebook or utilizing budgeting apps. By understanding where their money comes from and how it is spent, children can gain a clearer picture of their financial habits.

Earning and Saving Money
Part-time Jobs and Allowance
Encourage children to take on part-time jobs or offer them an allowance in exchange for completing chores or tasks. This provides them with a sense of responsibility and an opportunity to earn money. Teach them the importance of saving a portion of their earnings for future goals.
Opening a Savings Account
Introduce children to the concept of a savings account and help them open their own. Explain how interest works and emphasize the benefits of long-term saving. This encourages children to develop healthy saving habits from an early age.
The Power of Compound Interest
Explain the concept of compound interest and its potential to grow wealth over time. Help children understand the benefits of starting to save and invest early, as it allows their money to grow through compounding.
Making Informed Spending Decisions
Comparing Prices and Quality
Teach children to compare prices and evaluate the quality of products or services before making purchasing decisions. This helps them become discerning consumers and ensures they get the best value for their money.
Avoiding Impulse Purchases
Discuss the dangers of impulse purchases and the importance of thoughtful decision-making. Encourage children to pause and consider whether they truly need or want an item before making a purchase.
Understanding Advertising and Marketing Tactics
Educate children about advertising and marketing techniques used to influence consumer behavior. Teach them to recognize persuasive strategies, such as celebrity endorsements and limited-time offers, and to make informed choices based on their own needs and preferences.
Borrowing and Debt Management
Types of Loans
Introduce the concept of borrowing and explain the different types of loans, such as student loans, mortgages, and personal loans. Teach children about the responsibilities and consequences associated with borrowing money.
Credit Cards and Interest Rates
Discuss credit cards and their potential benefits and risks. Explain how interest rates work and emphasize the importance of paying credit card bills on time to avoid high interest charges.
Responsible Borrowing and Debt Repayment
Teach children the importance of responsible borrowing and managing debt effectively. Emphasize the need to prioritize debt repayment and avoid excessive borrowing that can lead to financial strain.
Investing and Growing Wealth
Introduction to Investments
Introduce children to the concept of investments and explain the potential for long-term wealth accumulation. Teach them about different investment options, such as stocks, bonds, and mutual funds.
Risk and Return
Help children understand the relationship between risk and return when investing. Teach them to assess their risk tolerance and make investment decisions based on their financial goals and time horizon.
Diversification and Asset Allocation
Explain the importance of diversification and asset allocation in investment portfolios. Teach children how spreading investments across different asset classes can help mitigate risks and maximize returns.
Teaching Financial Responsibility
Delayed Gratification
Instill the value of delayed gratification in children. Teach them that saving and planning for the future can lead to more significant rewards, rather than seeking immediate satisfaction through impulsive spending.
Philanthropy and Giving Back
Encourage children to develop a sense of social responsibility by introducing them to philanthropy. Teach them the importance of giving back to their community and supporting charitable causes.
The Role of Technology in Money Management
Mobile Apps and Online Tools
Discuss the various mobile apps and online tools available for money management. Teach children how to use these resources effectively to track expenses, set financial goals, and monitor their progress.
Digital Payment Methods
Explain the different digital payment methods, such as mobile wallets and online banking, and discuss their benefits and potential risks. Teach children about the importance of safeguarding their personal and financial information online.
Cybersecurity and Online Fraud Prevention
Educate children about cybersecurity and the importance of protecting their digital identities. Teach them about common online scams and how to identify and avoid them.
Money Lessons by Age
Children start forming money habits early. The Consumer Financial Protection Bureau (CFPB) notes that many basic money habits are taking shape by around age 7, and its “Money as You Grow” resources suggest age-appropriate goals. A simple roadmap:
- Ages 3 to 5: recognize coins and notes, understand that money is exchanged for things and practice waiting for something they want.
- Ages 6 to 10: use a “save, spend, share” system with three jars, compare prices, make small spending choices and live with the results.
- Ages 11 to 13: manage a regular allowance for some expenses, open a savings account, set a goal that takes several months to reach and learn how advertising and in-app purchases work.
- Teens: budget for clothes or activities, earn money from a part-time job, learn how paychecks, taxes, credit and interest work and start thinking about college costs. Our guide to financial education for teens covers this stage in detail.

Lead by Example and Talk About Money
Kids learn more from what they see than from what they are told. Let them watch you compare prices, use a shopping list, decline an impulse buy or move money into savings. Share age-appropriate details about family finances, such as how much the weekly groceries cost or how you are saving for a vacation, and explain trade-offs out loud: “If we eat out tonight, we will have less for the trip.” You do not need to share your salary to teach that money is limited and choices matter.
Allowance, Chores and Earning Money
Families handle this in different ways. Some pay an allowance with no strings attached, so children can practice budgeting; others link part of the money to extra chores beyond everyday family responsibilities, to show the connection between work and income. Either can work if you are consistent and let your child make choices with the money. Our guide to allowances for kids explains how to set an amount and adjust it over time.
Older children can also earn through small ventures such as pet sitting, yard work, crafts or a lemonade stand. Running a tiny business teaches pricing, costs, customer service and profit in a way no worksheet can.
Savings and Investment Accounts for Kids
- Kids’ savings accounts: many banks and credit unions offer accounts for minors with a parent as joint owner. Seeing interest added each month makes compound growth real. Check that the account is FDIC-insured (or NCUA-insured at a credit union) in the US.
- Custodial accounts: UTMA and UGMA accounts let an adult invest on a child’s behalf. The money legally belongs to the child, who takes control at an age set by state law, typically 18 or 21.
- Custodial Roth IRA: available if your child has earned income, for example from a part-time job, and a powerful way to show long-term investing.
- UK options: children’s savings accounts and the Junior ISA, which lets families save or invest tax-free until the child turns 18. Check the current annual allowance on GOV.UK.
For ideas that make saving fun, see teaching kids the value of saving.

What Schools and Communities Can Add
Financial lessons fit naturally into math (percentages, interest, budgets), social studies (economics, taxes) and project-based learning. A growing number of US states require a personal finance course for high school graduation, and many banks and credit unions run free programs for schools. At home, ask what your child is learning and reinforce it with real examples. For games, books and free classroom resources, see our guide to fun ways to teach kids financial literacy.
Review and Adjust as They Grow
Check in every few months: is the allowance still the right size, are savings goals realistic and is your child ready for more responsibility, such as a debit card with parental controls? Mistakes made with small amounts of money now are some of the cheapest lessons your child will ever get.
More guides on kids and money
- Fun ways to teach kids about money: games, books and free resources.
- Teaching kids to save: activities and lessons by age.
- Allowances for kids: using pocket money to teach budgeting.
- Teaching kids about credit and debt: interest and borrowing explained simply.
- Financial education for teens: money skills for college and beyond.
Conclusion
Teaching money management skills to children and young adults is a vital investment in their future. By imparting knowledge about budgeting, saving, responsible borrowing, investing, and financial responsibility, parents and educators can equip them with the tools they need to navigate the complexities of the financial world successfully.
FAQs
Q: At what age should I start teaching my child about money management?
A: It is never too early to start teaching children about money. Basic concepts can be introduced as early as preschool age, and gradually more complex topics can be introduced as they grow older.
Q: How can I make money management lessons fun and engaging for children?
A: Incorporate games, interactive activities, and real-life examples to make money management lessons enjoyable and relatable. Use hands-on experiences, such as letting children handle money and make their own financial decisions within limits.
Q: What are some practical ways to encourage saving in children?
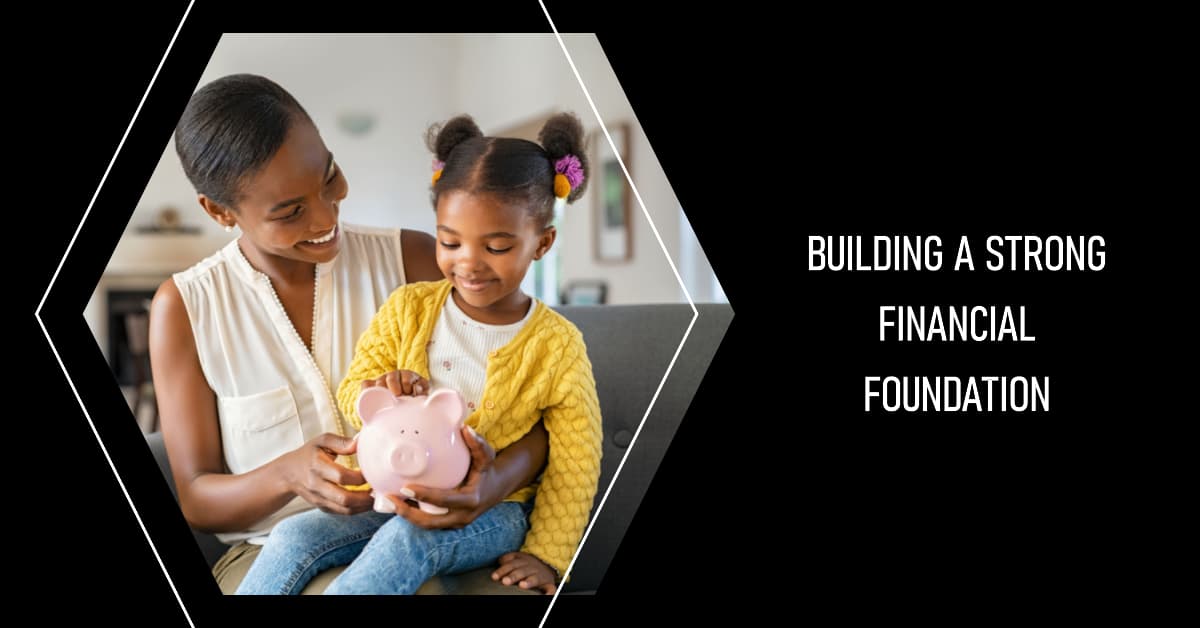
A: Provide children with piggy banks or savings jars to physically see their money grow. Set savings goals and offer incentives or matching contributions to motivate them.
Q: How can I teach my child the value of giving back?
A: Involve children in volunteering activities or encourage them to donate a portion of their savings to a cause they care about. Explain the positive impact their contributions can have on others.
Q: Are there any recommended resources or apps to assist in teaching money management to children?
A: Yes, several resources and apps are available, such as “Money Savvy Pig,” “PiggyBot,” and “Bankaroo,” which offer interactive platforms for children to learn and practice money management skills.